We may earn a commission if you buy through links on this page. It never changes a score or a ranking. How we make money
The bottom line
A unified payments API for ACH and real-time rails, sold through custom pricing.
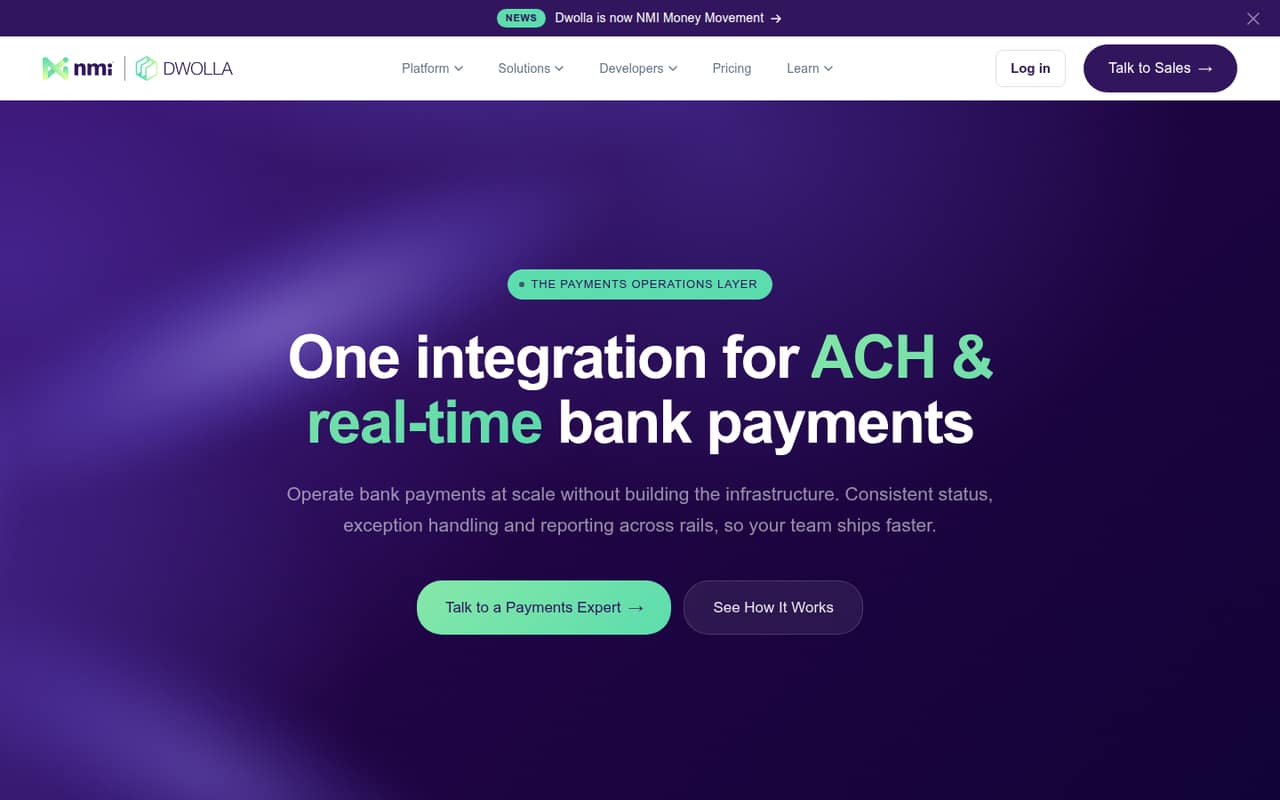
Dwolla is a hosted payments platform for businesses embedding money movement in their products. Its API connects Standard ACH, Same Day ACH, RTP Network and FedNow Service, with shared payment statuses, exception handling and reporting. The platform also lists webhooks, a dashboard, mass pay, digital wallets and drop-in components.
The fit is strongest for teams that want one managed integration across bank-payment rails. Pricing is custom, and the vendor does not list a free plan or numeric starting price. Confirm SDK support, transaction economics, reliability commitments and data portability with sales before building around it.
Good fit if
- Platforms embedding bank payments
- Teams consolidating payment rails
- Businesses automating payouts and collections
Skip it if
- Developers seeking a free API tier
- Teams requiring self-hosted payment infrastructure
- Projects needing published per-transaction pricing
ScoresHow it rates
What works
- One API across ACH and real-time rails
- Supports Standard ACH and Same Day ACH
- Access to RTP Network and FedNow Service
- Standardized status tracking and exception handling
- Includes webhooks, mass pay and drop-in components
What doesn't
- Custom pricing has no published starting figure
- No free plan is listed
- SDK languages and CLI support need confirmation
- No self-hosting option is published
- Data export and migration terms need confirmation
01What Dwolla is, technically
Dwolla is a hosted payments platform with an API, not a self-hosted server, payments library or standalone CLI. It sits between an application and the bank-payment rails its product needs, handling payment initiation and the operational layer around payment status, exceptions and reporting.
The API unifies Standard ACH and Same Day ACH with access to the RTP Network and FedNow Service. That gives a product team one integration surface for several bank-payment options rather than separate rail-specific integrations. Dwolla also lists a digital wallet, dashboard, mass pay, drop-in components and webhooks as platform tools.
The intended customers are businesses and platforms embedding payments, including B2B, real estate, lending, insurance and healthcare products. The company’s homepage says Dwolla is now NMI Money Movement. For an architecture review, treat it as a managed dependency for moving money: your application still needs to handle user flows and business rules, while Dwolla provides payment infrastructure and operational visibility.
02Dwolla API, SDKs and docs
The core integration surface is Dwolla’s API, supported by developer documentation, a sandbox and platform support. The homepage presents a unified integration across ACH and real-time rails, with standardized payment statuses, exception handling and reporting. Webhooks are listed as a feature for receiving payment-related events; the dashboard, mass pay, digital wallet and drop-in components provide additional platform tools.
The vendor’s homepage does not name SDK languages, an API protocol or a CLI. Confirm SDK availability and support for your language in Dwolla’s developer docs before estimating implementation effort. Ask whether the API uses the authentication, event-delivery and versioning patterns your stack requires, and review webhook retries and idempotency behavior before relying on event-driven workflows.
The sandbox gives teams a place to evaluate integration behavior, but production readiness also depends on onboarding and payment-flow requirements. Map your own ledger and reconciliation needs against Dwolla’s status and reporting model before choosing how much payment state to mirror in your application.
03Dwolla pricing for developers
The pricing page lists custom pricing for businesses seeking payment processing. It describes multiple payment rails and no surprise add-ons, but gives no monthly or annual figure and no numeric starting price. The pricing information is low confidence, so treat it as a prompt to get a written quote rather than a cost estimate.
Dwolla does not list a free plan or a free-trial period. The vendor also does not publish transaction fees, volume bands, request charges, seat pricing, overages or add-on prices. As a result, we cannot calculate how a bill changes with payment volume or compare the unit economics with a per-transaction alternative.
Before committing, ask sales for a complete schedule covering ACH and real-time transactions, returns, failed payments, account verification, minimums, implementation and support. Request examples using your expected monthly volume and payment mix, and establish how pricing changes if volume or rail usage grows. The custom quote means value depends on negotiated costs and the operational work the unified integration replaces.
04Dwolla: open source, self-hosting and lock-in
Dwolla is presented as a managed payments platform accessed through its API, not as a self-hosted server or open-source library. The vendor does not publish an open-source license or self-hosting option. That makes Dwolla a hosted dependency: payment execution and platform availability sit outside your infrastructure.
The product pages do not describe data-export formats or a migration path. Ask what transaction, customer and reconciliation data you can export, how long it remains available after termination, and whether exports include the identifiers and statuses your ledger needs. Also clarify how to handle payments in flight if you switch providers.
The API may reduce the code needed to integrate multiple rails, but it does not remove provider lock-in. Keep your internal payment model and reconciliation logic independent of Dwolla-specific fields where practical, and document a migration plan before launch. Confirm contract terms and export access directly with the vendor.
05Dwolla in production
Dwolla’s homepage reports 99.9% platform uptime and lists tokenization, instant bank verification and 24/7 platform monitoring as security features. Those claims are not substitutes for reviewing the contract: confirm uptime definitions, support escalation, maintenance windows, incident communications and remedies. Ask for current security and compliance documentation relevant to your use case.
The API unifies several rails, but payment timing and failure handling still matter. Confirm rail eligibility, processing cutoffs, return behavior, webhook delivery and recovery procedures for each payment type. Load and rate limits, request quotas and published service-level details need confirmation with Dwolla before sizing a high-volume integration.
Reddit discussion is limited and mostly consumer or partner context, not current API-operator evidence. One older consumer comment says bank-to-Dwolla transfers took “about 3 to 4 days”; that is not a reliable measure of present API settlement or ACH timing. A property-management discussion describes a partner removing Dwolla ACH, illustrating that downstream product availability can change. Validate your own use case and dependencies with the vendor.
From the threadsWhat users say
The available Reddit discussion is mixed but thin and does not provide a current, representative view of Dwolla API customers. Comments include a dated consumer complaint about transfer time and a partner-platform discussion about Dwolla ACH being removed; neither establishes current API reliability.
the time it takes to move from bank to Dwolla is about 3 to 4 days
Dwolla ACH bank transfers (no fees on either side)
Just got the email. I'm out too. I paid the whole year though so I'm salty
I have used plaid, MX, Dwolla and more
Questions people ask
What is Dwolla?
Dwolla is a hosted payments platform for businesses embedding money movement in their products. Its API connects Standard ACH and Same Day ACH with access to the RTP Network and FedNow Service. The platform also lists payment tracking, exception handling, reporting, webhooks, mass pay, a dashboard and digital wallet tools.
How much does Dwolla cost?
Dwolla uses custom pricing for businesses seeking payment processing. The pricing page does not publish a numeric starting price, transaction fees or volume-based rates, and it does not list a free plan. Ask sales for a written quote based on your expected rails, transaction volume, returns, verification needs and support requirements.
Is Dwolla legitimate and trustworthy?
Dwolla presents itself as a payments platform for businesses and reports 99.9% platform uptime. It lists tokenization, instant bank verification and 24/7 platform monitoring. Those claims do not replace due diligence: review current security and compliance documentation, service commitments, incident procedures and the payment flows relevant to your business.
What payment methods does Dwolla support?
Dwolla lists Standard ACH and Same Day ACH, plus access to the RTP Network and FedNow Service. Its homepage also lists Push to Card among payment methods. Confirm which rails and features are available for your business, use case and customer accounts, and ask about timing, eligibility and transaction costs.
Who bought Dwolla?
Dwolla’s homepage announces, “Dwolla is now NMI Money Movement.” That identifies the current brand presented on the site, but does not provide transaction details. If ownership, contracting entity or service continuity matters to your procurement review, confirm those details with the vendor before signing.
Sources
- Dwolla homepage
- Dwolla pricing, compiled via web search from dwolla.com, apis.io, paymentreview.com
- Reddit: Dwolla: an online payment system that sidesteps credit cards
- Reddit: I have built 8 personal finance management apps & solutions. AMA.
- Reddit: Dwolla Email
- Reddit: TenantCloud is dropping Dwolla ACH-based fee-free payments in favor of Stripe for-fee payments. What alternatives are there out there?